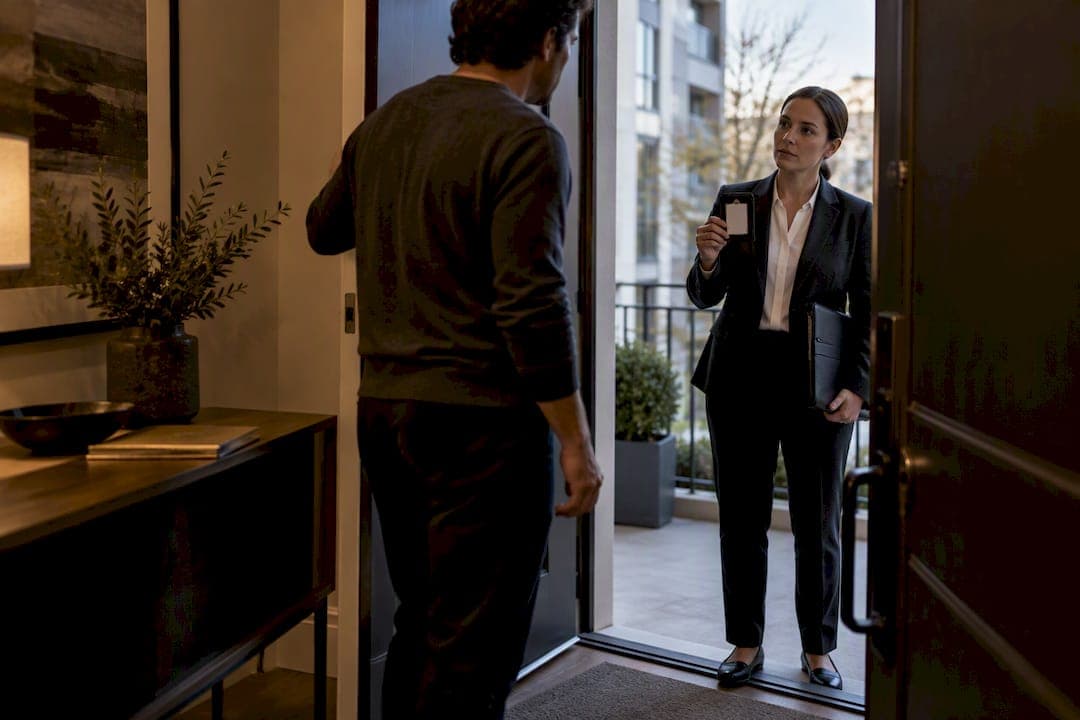
A revenue officer visit usually means your unpaid tax balance or unfiled returns have moved past routine notices into active civil collection, a resolve-or-enforce stage. Most contacts now start with a scheduled Letter 725-B rather than a knock at the door, so your first move is to verify the letter, confirm the appointment, and gather the records it requests. If you would rather not handle the meeting alone, you can file Form 2848 immediately to authorize a representative to speak for you.
TL;DR:
- Most revenue officer contacts now involve scheduled appointments verified through Letter 725-B, not unannounced visits, to reduce scams and confusion.
- Confirm the officer’s identity by calling the number on the letter or checking your IRS online account before discussing sensitive information.
- Prepare Form 433-A or 433-B and gather financial documents in advance, avoiding pressure to fill out forms during the meeting for accuracy.
- Enforcement steps may include installment plans, offers in compromise, liens, levies, or asset seizures, with strict deadlines driving the process.
- Having professional representation helps ensure accurate record assembly, proper negotiation, and minimizes the risk of costly mistakes during enforcement.
Table of Contents
- Who revenue officers are and why one is assigned to your case
- Letter 725-B and how to confirm your appointment is real
- What to expect at the meeting: documents and questions
- Verifying identity and knowing your rights during contact
- How to prepare and what to say when contact happens
- Likely outcomes, enforcement steps, and deadlines that matter
- How The Tax Refinery prepares clients for a revenue officer visit
- Why speed and documentation matter more than confidence
- How The Tax Refinery can help with a revenue officer case
- Sources
- FAQ
Who revenue officers are and why one is assigned to your case
Revenue officers work civil field collection. Their job is to resolve delinquent balances, secure missing returns, and move stalled cases toward a plan or an enforcement action. The IRS typically assigns one when a balance is large, when earlier notices went unanswered, or when a business has unfiled payroll returns or unpaid employment taxes.
It helps to know who is not showing up at your door:
- A revenue officer handles civil collection, not audits or criminal cases.
- A revenue agent examines returns for accuracy, which is a separate audit function.
- A Criminal Investigation special agent works fraud and criminal tax cases, a different track entirely.
Knowing which category applies tells you how serious the contact is and what kind of response fits. A revenue officer visit is a collection matter with real consequences, but it is not a criminal proceeding.
Letter 725-B and how to confirm your appointment is real
Since July 2023, the IRS ended most unannounced revenue officer visits and replaced them with scheduled appointment letters, largely to cut down on confusion and reduce the risk of scams. Letter 725-B is that appointment letter, and it names the assigned officer, gives a direct phone number, sets a meeting or contact-by date, and lists the records you need to bring.
Before you do anything else, take these steps:
- Call the phone number printed on the letter itself, not a number someone gives you over the phone.
- Log into your IRS online account to confirm the case and officer name match what the letter says.
- If someone shows up in person, ask to see two forms of official identification before discussing anything.
If no letter ever arrived and someone claims to be a revenue officer at your door, treat that as suspect. The IRS notes that unannounced visits are now rare and limited to specific situations such as serving a summons or seizing assets, so verify first and never hand over money or personal information until you have confirmed the person's identity.
What to expect at the meeting: documents and questions
The officer's meeting is a financial fact-finding session, not a negotiation you can improvise. Expect to bring unfiled returns, usually covering several prior years, along with bank statements, payroll records, general ledgers, proof of income, and current bills.
Two forms carry the most weight:
- Form 433-A collects a financial statement for individuals and sole proprietors.
- Form 433-B collects the same information for businesses and partnerships.
- Form 9297 is the officer's written summary of what was discussed and what is due next, according to IRM collection procedures.
Expect direct questions about your income sources, assets, monthly living or business expenses, and your realistic ability to pay. The officer is building a financial picture to decide which collection path fits your case, so vague or incomplete answers tend to slow things down rather than help you. If your situation involves payroll, our guide to Trust Fund Recovery Penalty exposure covers records you should assemble before the meeting.
Pro Tip: Fill out Form 433-A or 433-B before the meeting, not during it. Numbers you write under pressure are harder to correct later.
Verifying identity and knowing your rights during contact
A legitimate revenue officer carries two forms of official IRS identification, each with a serial number, and will let you note both before any conversation continues. You can also confirm identity by calling the number on your Letter 725-B or checking your IRS online account rather than trusting a business card or a badge alone.
Watch for these warning signs of a scam:
- A demand for immediate payment through gift cards, wire transfers, or cryptocurrency.
- Refusal to provide two forms of ID or a callback number.
- Pressure to keep the visit secret from a spouse, accountant, or attorney.
The IRS ended most unannounced visits in 2023 partly to shrink this exact opening for impersonation scams, so an unscheduled knock at your door is itself a reason to slow down.
You have rights that a legitimate officer will respect. You can decline entry into your home, ask to meet at an IRS office instead, request time to gather records, and bring a representative. You do not have to consent to a search of your property without a court order.

How to prepare and what to say when contact happens
Preparation starts before the officer ever calls. Verify the letter, pull together the records requested, draft your Form 433-A or 433-B in advance, and gather proof of any recent payments or filings. Make copies of everything before you hand originals to anyone.
A simple sequence works for the actual conversation:
- Verify identity using the letter's phone number or your IRS online account.
- Ask directly what the visit is about and which documents the officer still needs.
- Request time to gather records, or name a representative and pause further discussion until they are involved.
- Ask the officer to confirm next steps and deadlines in writing.
Our audit preparation checklist covers similar document-gathering steps that apply here as well. During the meeting itself, avoid admitting to willful wrongdoing, avoid guessing at income or asset figures you cannot document, and avoid writing a large check on the spot without paperwork confirming what it resolves.
Pro Tip: If you are unsure how to answer a question, say you will follow up in writing rather than estimating out loud.
Likely outcomes, enforcement steps, and deadlines that matter
Once the officer has your financial picture, several paths open up. Some resolve the balance, others escalate it.
- An installment agreement spreads the balance over time based on documented ability to pay.
- An offer in compromise settles for less than owed, but eligibility is limited and reviewed closely.
- A notice of federal tax lien can be filed to protect the government's claim against your property.
- A levy can reach a bank account or wages if the case stalls without a plan.
- A substitute return may be filed on your behalf if you never file, often producing a higher balance than a self-prepared return.
- Seizure of physical assets is rare but remains available for the most stalled cases.
Deadlines drive all of it. The date on your Letter 725-B, the 30-day window tied to a final notice before a levy, and the 10-business-day window to appeal a seizure through the Collection Appeals Program are not flexible on their own. Filing missing returns, proposing a documented payment plan, or submitting Form 2848 to bring in a representative often pauses enforcement while the case moves toward a resolution. Our overview of IRS payment plan options walks through how those agreements typically work for business owners.
How The Tax Refinery prepares clients for a revenue officer visit
A tax advisory firm organizes client records, drafts accurate Form 433-A and 433-B statements, and files Form 2848 so a representative can speak directly with the assigned officer. For business owners, the firm places early emphasis on payroll and employment-tax records, since trust-fund recovery exposure tends to surface fast once a revenue officer opens a business case.
Why speed and documentation matter more than confidence
Enforcement rarely surprises taxpayers who respond early and in writing. What surprises people is waiting, hoping the letter was a mistake, or answering questions verbally that should have gone through a representative first. Choosing representation is not giving up control. It is putting one professional voice between you and every deadline.
— Melissa
How The Tax Refinery can help with a revenue officer case
Facing a revenue officer alone means answering financial questions in real time with no one checking the numbers behind you. A tax advisory service can act as your representative under Form 2848, assemble the financial statements the officer will request, and negotiate installment agreements or other collection resolutions on your behalf, while filing any delinquent returns that triggered the case.
If you have received a Letter 725-B, send us a copy along with your most recent filed returns and we will tell you exactly what the officer still needs before your appointment date. Review our tax strategy and advisory options to see how ongoing representation works, or explore tax resolution services to get started today.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Does the IRS still have revenue officers?
Yes, revenue officers remain part of the IRS field collection staff and continue to work delinquent balance and unfiled return cases. Since 2023, most of their initial contact comes through a scheduled Letter 725-B rather than an unannounced visit.
Why would the Department of Revenue come to my house?
A visit typically follows a large unpaid federal tax balance, unfiled returns, or an unresolved business payroll issue that earlier notices did not fix. Most home visits today are scheduled in advance, so an unannounced one is worth verifying carefully.
Are revenue officers law enforcement?
No, revenue officers handle civil tax collection, not criminal law enforcement. Criminal tax matters are handled separately by IRS Criminal Investigation special agents, a distinct division with different authority.
Does the IRS come to your house unannounced?
Rarely. The IRS ended most unannounced revenue officer visits in 2023 and now schedules meetings through Letter 725-B, with unannounced contact limited to specific situations such as serving a summons or carrying out a seizure.