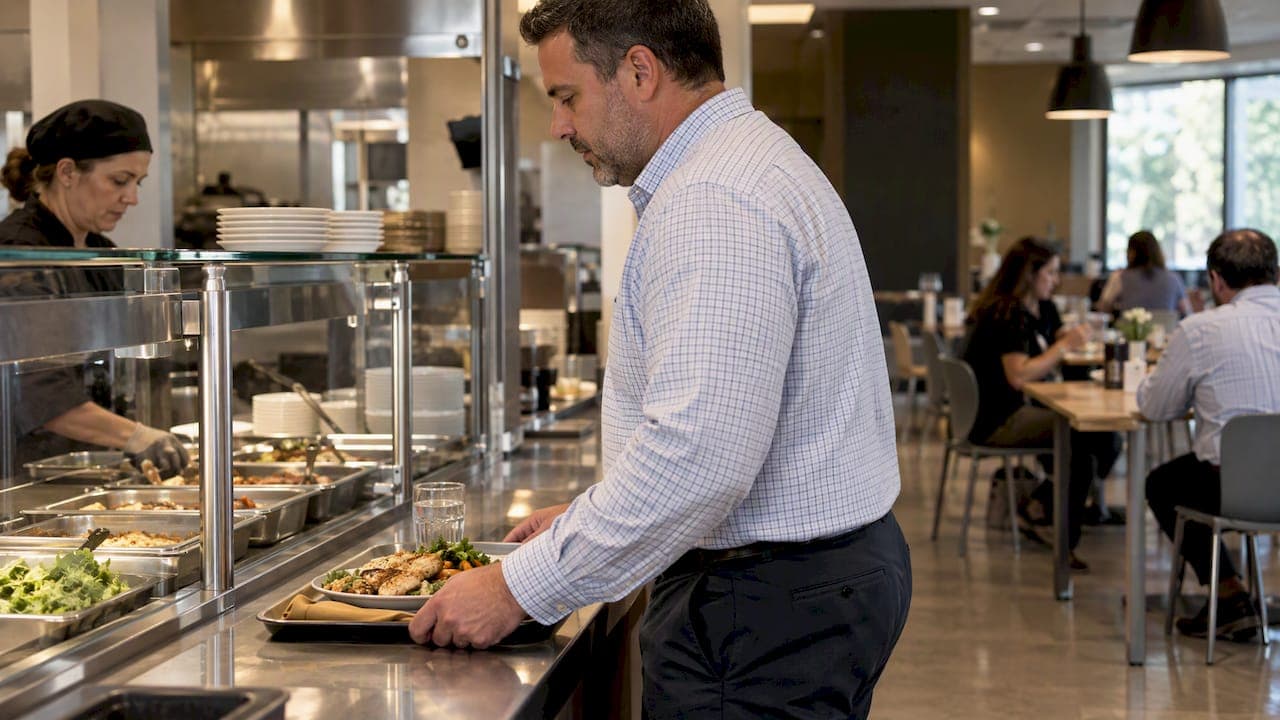
Qualifying business meals stay at a 50% deduction in 2026 when you or an employee are present, the food is not lavish, and the purpose is business related. Entertainment expenses remain generally nondeductible. The bigger shift lands on employer-provided meals: most on-site cafeterias, breakroom food, and employer-operated eating facilities lose their deduction entirely for amounts paid after December 31, 2025, with only narrow exceptions surviving.
TL;DR:
- A separately stated food and beverage charge at an entertainment event can retain the 50% deduction, although the surrounding entertainment expense generally remains nondeductible.
- Employee parties can remain fully deductible when they benefit staff broadly, while meals treated as taxable employee compensation also escape the meal deduction limits.
- Per diem rates simplify substantiation when reports match federal locality rates; actual cost tracking may yield larger deductions in expensive cities but requires receipts.
- Meal records should include the date, amount, location, business purpose, attendees, and itemized invoices; retain them at least three years from filing.
- Food sold directly to the public falls outside meal deduction limits because it counts as the cost of goods sold.
Table of Contents
- What Changed for 2026: Statutes, Scope, and Employer Impacts
- Which Meals and Entertainment Remain Deductible in 2026
- Exceptions That Can Be 100% Deductible
- Per-Diem and Travel Meals: Rates, Rules, and the 50% Limit
- Recordkeeping and Substantiation: What Auditors Actually Want to See
- Practitioner Playbook: Bookkeeping Controls for 2026
- How We Advise Clients Facing the 2026 Changes
- How The Tax Refinery Helps You Get This Right
- FAQ
- Sources
- Essential Authoritative Links
What Changed for 2026: Statutes, Scope, and Employer Impacts
The statutory change takes effect for amounts paid or incurred after December 31, 2025, and it targets a specific category: meals provided for the convenience of the employer and meals from employer-operated eating facilities. These had been 50% deductible under prior law. Starting in 2026, that deduction mostly disappears.
This affects common setups: company cafeterias, stocked breakrooms, free lunches provided during working meetings, and similar on-premises food programs. A handful of narrow exceptions remain, tied to specific industries and facility arrangements, but the default rule for 2026 is nondeductible. IRS Publication 463 confirms the 50% limitation structure that governs the categories that do remain deductible.
For employers, the practical response starts now:
- Reclassify on-site meal and cafeteria accounts to a 0% deductible bucket before your first 2026 filing.
- Decide whether any remaining employer-provided meals should be reported as taxable wages instead of a tax-free fringe benefit.
- Update written expense policies so staff and bookkeepers code these costs correctly at the point of entry, not during year-end cleanup.
Which Meals and Entertainment Remain Deductible in 2026
The baseline 50% rule survives the 2026 changes largely intact, and it covers more ground than many business owners assume. A meal qualifies for the 50% deduction when three conditions are met: you or an employee is present at the meal, the food and beverages are not lavish or extravagant under the circumstances, and the expense serves a genuine business purpose. Publication 463 lays out this standard directly, and it applies whether you are buying lunch for a prospect or grabbing dinner on a business trip.
Entertainment, amusement, and recreation costs sit on the other side of the line and are generally nondeductible, a rule that has held since the 2017 tax law changes and continues unchanged into 2026. The exception worth knowing: when a vendor invoice separately states the food and beverage charge at an entertainment event, that meal portion can still qualify for the 50% deduction even though the surrounding entertainment cost does not.
| Expense type | 2026 deductible percentage |
|---|---|
| Client or prospect business meal | 50% |
| Travel meal (employee traveling for business) | 50% |
| Entertainment, amusement, or recreation | Generally 0% |
| Food charge separately stated on an entertainment invoice | 50% |
| Most employer-provided on-site meals (cafeterias, breakrooms) | Generally 0% after 2025 |
Exceptions That Can Be 100% Deductible
A handful of categories escape both the 50% limitation and the entertainment disallowance entirely, and knowing them helps you avoid underclaiming legitimate expenses.
- Employee recreation and social events, such as holiday parties or company picnics, can remain fully deductible when they primarily benefit employees rather than a select group of executives.
- Meals treated as taxable compensation to an employee, meaning the value is included in their W-2 wages, are no longer subject to the meal limitations because they are treated as ordinary wage expense instead.
- Food or beverages sold to the public, such as meals provided by a restaurant to paying customers, fall outside the meal deduction rules altogether since they are simply cost of goods sold.
- Reimbursements under a properly structured accountable plan preserve the underlying deduction category; sloppy or informal reimbursement practices can push the expense into taxable wage territory instead.
Per-Diem and Travel Meals: Rates, Rules, and the 50% Limit
Business travel adds a second set of rules on top of the baseline meal deduction. Employers and the self-employed can choose between tracking actual meal costs or using the federal Meals and Incidental Expenses (M&IE) per-diem rates, which vary by locality and are published through GSA tables. Publication 463 directs taxpayers to those locality tables and explains how the per-diem method works for substantiation purposes.
Choosing per-diem does not create a bigger deduction; it simplifies the paperwork needed to support it. A few practical points matter when choosing a method:
- Per-diem amounts are treated as substantiated for the IRS when an employee's expense report matches the applicable federal rate, cutting down on receipt collection.
- Actual-cost tracking can produce a larger deduction in high-cost cities but requires complete receipts and documented business purpose for every meal.
- An accountable plan has to be properly drafted and administered; without one, per-diem payments risk becoming taxable wages rather than a clean reimbursement.
Smaller firms with frequent travel tend to favor per-diem for its audit resilience and lower administrative burden, while firms with concentrated high-cost travel sometimes do better tracking actual costs.
Recordkeeping and Substantiation: What Auditors Actually Want to See
Section 274 imposes substantiation requirements that go well beyond keeping a receipt. For any claimed meal expense, you need to document:
- The date the expense was incurred.
- The amount paid, including tax and tip.
- The place where the meal occurred.
- The specific business purpose or topic discussed.
- The names and business relationship of everyone present.
Keep the itemized invoice along with a contemporaneous note describing the business discussion that took place.
Retain these records for at least three years from the filing date, though many practitioners recommend seven years given how often meal and entertainment classifications draw audit attention. The most common red flag examiners look for is a round-number pattern with no attendee detail, which signals estimated rather than contemporaneous recordkeeping.
Pro Tip: Keep a simple shared log (a spreadsheet or app note) where staff enter attendee names and business purpose the same day as the meal, not weeks later during bookkeeping cleanup.

Practitioner Playbook: Bookkeeping Controls for 2026
We build our client systems around one principle: classification at the point of entry beats reconstruction at tax time.
A few changes worth making before year-end:
- Update your expense-submission policy to require business purpose and attendee names on every meal receipt over a modest threshold.
- Review your accountable plan documentation to confirm reimbursements still qualify as nontaxable rather than drifting into wage territory.
- Add a memo field requirement for any invoice that mixes entertainment and food charges.
- Build a quarterly reconciliation step where someone other than the person who submitted the expense confirms the coding before it hits your books.
Pro Tip: Run a quarterly export of your meals and entertainment accounts and spot-check ten transactions against the Section 274 substantiation checklist. Catching a miscoded cafeteria expense in March is far less painful than catching it during an audit.
For S-Corp owners managing payroll alongside these changes, our guide on accountable plan rules walks through the three IRS tests that keep reimbursements out of taxable wages.
How We Advise Clients Facing the 2026 Changes
We spend the first conversation with every new client identifying where meal and entertainment spending is miscoded, because that single category causes more audit friction than almost any other line item. Our priority order is consistent: reclassify accounts first, review the accountable plan second, then run a year-end cleanup before the books close.
— Melissa
How The Tax Refinery Helps You Get This Right
Sorting out which 2026 meal and entertainment rules apply to your business takes more than a one-time read of IRS guidance. It takes a system that keeps updating as your bookkeeper, your point-of-sale vendor, and your accountable plan all interact.
Our Monthly Tax Advisory and Quarterly Tax Strategy Sessions build the chart-of-accounts structure, card-feed rules, and accountable-plan documentation that keep your meal and entertainment deductions audit-ready year round, not just at filing time. For S-Corp owners navigating payroll alongside these changes, our S-Corp Tax Strategy Accelerator covers the entity-level planning that often intersects with reimbursement policy.
A few ways to get started:
- Book a policy review to reclassify your meal and entertainment accounts before your next filing.
- Add an accountable-plan audit to confirm your reimbursements still qualify as nontaxable.
- Combine either service with our standard tax preparation work so the coding carries straight through to your return.
Compare our advisory plans and pick the engagement that matches how often your meal and entertainment spending needs attention.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What is the IRS meal allowance for 2026?
There is no single flat "meal allowance" for 2026. For travel, you can use actual costs or the federal M&IE per-diem rates published by locality, but either way the result is subject to the standard 50% deduction limit described in Publication 463.
How does the new $6,000 deduction work?
There is no standard federal meals-and-entertainment deduction set at $6,000.
How much can you claim for meals and entertainment?
Qualifying business meals are generally 50% deductible under IRC §274 when you or an employee are present and the expense serves a business purpose.
What meals and entertainment expenses are 100% deductible?
Employee recreation events like holiday parties, meals treated as taxable wages included in an employee's W-2, and food or beverages sold directly to the public can all qualify for full deductibility.
Sources
- Publication 463 (Travel, Gift, and Car Expenses) | Internal Revenue Service
- 26 U.S.C. §162 — Trade or business expenses
- Revenue Procedure (per-diem guidance) | IRS
Essential Authoritative Links
- Publication 463 (Travel, Gift, and Car Expenses) | Internal Revenue Service
- 26 U.S.C. §162 — Trade or business expenses
- Revenue Procedure (per-diem guidance) | IRS