A vehicle with a gross vehicle weight rating of 6,000 lbs or more (and up to 14,000 lbs) can qualify for a Section 179 deduction of $32,000, plus bonus depreciation on the remaining basis. The catch: you must use it more than 50% for business, and your write-off is capped at that business-use percentage. Deduct aggressively without documentation, and you're setting up a recapture problem down the road.
TL;DR:
- Vehicles with a manufacturer's GVWR of 6,000 lbs or more are eligible for a $32,000 Section 179 deduction in 2026, provided they are used over 50% for business.
- After applying the Section 179 cap, bonus depreciation can be claimed at 100% on the remaining basis, potentially allowing the entire business-use cost to be deducted in year one.
- Proper documentation, including a GVWR certification, mileage logs, and a business purpose memo, is essential to avoid recapture issues and withstand IRS audits.
- The vehicle must be classified correctly as either a passenger vehicle or a non-passenger cargo/utility vehicle to determine the correct deduction limits and caps.
- State tax rules may differ, so verifying local conformity is necessary, especially for multi-state operations or international vehicle registration.
Table of Contents
- How Much Can You Deduct Under the 6,000 lb Vehicle Rule?
- Does Your Vehicle Qualify? GVWR and the Business-Use Test
- What Triggers Recapture and How Do You Prepare for an Audit?
- How Do You Report the Deduction on Your Tax Return?
- When Does Buying a Heavy Vehicle Actually Make Sense?
- What Counts as a '6,000 lb Vehicle' Under IRS Rules?
- Which Vehicles Typically Meet the 6,000 lb GVWR Threshold?
- Can Modifications Change a Vehicle's Weight Eligibility?
- How Does This Deduction Interact With Luxury Auto Limits?
- Passenger Vehicles vs. Non-Passenger Vehicles: Why the Distinction Matters
- Do State Taxes Change How This Deduction Works?
- What Melissa Korber Has Learned Advising Clients on Vehicle Deductions
- Get Audit-Proof Vehicle Deduction Planning From The Tax Refinery
- FAQ
How Much Can You Deduct Under the 6,000 lb Vehicle Rule?
The math runs in a specific order, and skipping a step is the most common mistake we see. For 2026, Publication 946 sets the Section 179 expensing cap for SUVs with a GVWR between 6,000 and 14,000 lbs at $32,000. That's separate from the overall Section 179 limit, which sits at $2,560,000 for 2026, phasing out once total qualifying purchases cross $4,090,000.

Once you've applied the Section 179 cap, whatever basis remains is eligible for bonus depreciation. Under the One Big Beautiful Bill, bonus depreciation is now a permanent 100% deduction for qualifying property placed in service after January 19, 2025.
Here's how the sequence plays out on a $70,000 heavy SUV used 80% for business:
- Business-use basis: $70,000 × 80% = $56,000
- Section 179 deduction: $32,000 (the SUV cap)
- Remaining basis: $24,000
- Bonus depreciation at 100%: $24,000
- Total first-year deduction: $56,000
That's the entire business-use basis written off in year one, legally. It's also why heavy vehicles draw more attention from the IRS than a standard sedan.
Does Your Vehicle Qualify? GVWR and the Business-Use Test
Two gates determine whether you get anywhere near that $56,000 figure: weight classification and usage percentage.
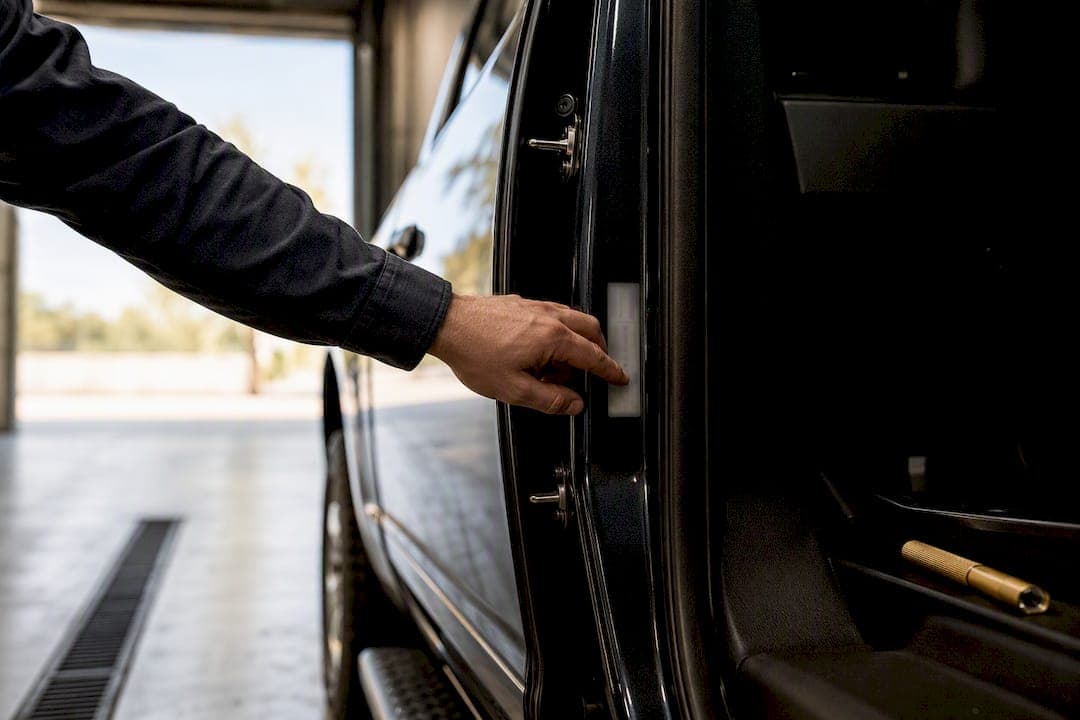
- Check the GVWR sticker, not the curb weight. The gross vehicle weight rating, found on the driver's door jamb, must read 6,000 lbs or higher to escape the strict passenger-auto depreciation caps under §280F. Curb weight (the vehicle empty) is irrelevant; GVWR includes maximum passenger and cargo load.
- Confirm business use exceeds 50% in the year the vehicle is placed in service, as required under Topic No. 510. Fall short and you lose access to Section 179 and bonus depreciation entirely, defaulting to slower straight-line depreciation.
- Calculate your business-use percentage from a mileage log or actual-expense allocation, then apply that percentage to the vehicle's cost before applying any caps.
Commuting from home to your regular office doesn't count as business use, no matter how many client calls you take on the drive. Neither does using the truck for a family trip on weekends, even if you occasionally toss in a tool bag. Our guide on mileage versus actual expense tracking breaks down which method fits which situation, but either way, the IRS expects contemporaneous records: a mileage log kept in real time, not reconstructed from memory in March.
What Triggers Recapture and How Do You Prepare for an Audit?
Recapture is the mechanism that turns yesterday's deduction into today's tax bill. If you sell the vehicle, or if business use drops below 50% in a later year, some or all of that accelerated depreciation gets recaptured as ordinary income in the year of the change. Practitioners see this catch clients off guard constantly. One analysis of vehicle depreciation recapture notes that owners often treat Section 179 and bonus depreciation as free money rather than a timing tool, and the recapture bill can land years after the purchase, when the cash from the original deduction is long spent.
A few patterns reliably draw IRS scrutiny:
- A luxury or oversized vehicle purchase that looks disproportionate to the size of the business
- Thin or missing mileage records, especially logs that appear to have been created after the fact
- A sharp drop in reported business-use percentage from one year to the next
- Vehicle expenses that don't match up with other reported business activity
Pro Tip: Write a dated, signed business-purpose memo the day you buy the vehicle, explaining exactly why the business needs it, and start your mileage log on the placement-in-service date, not weeks later. Auditors specifically look for a continuous log beginning at acquisition.
How Do You Report the Deduction on Your Tax Return?
Every Section 179 and bonus depreciation election flows through one form, then lands on your business return.
- File Form 4562 to elect Section 179 and claim bonus depreciation, listing the vehicle, its cost, business-use percentage, and the depreciation method.
- Carry the deduction to your business return: Schedule C for sole proprietors, Form 1120-S for S corporations, or Form 1065 for partnerships, depending on how your business is structured.
- Apply the math in order: multiply cost by business-use percentage first, apply the $32,000 SUV cap, then apply bonus depreciation to what's left, exactly as shown in the earlier example.
- Keep the paper trail: the purchase invoice, a copy of the GVWR specification sheet, your contemporaneous mileage log, the business-purpose memo, and documentation of the exact placement-in-service date.
Missing any one of these documents doesn't necessarily kill the deduction, but it weakens your position significantly if the return gets pulled for review. Entity type matters here too. An S corporation claiming the deduction has different reporting mechanics than a sole proprietor, and how the vehicle interacts with your accountable plan can change who actually benefits from the write-off.
When Does Buying a Heavy Vehicle Actually Make Sense?
Buying a truck in December because your accountant mentioned a tax deduction is how recapture problems get started. Run through this before you sign anything:
- Does the business genuinely need this vehicle, independent of the tax benefit?
- What percentage of use will realistically be business, not just in year one but for the next three to five years?
- Can your cash flow absorb the purchase, or are you financing a deduction you can't actually afford?
- What's the vehicle's expected resale value, and how much recapture would that trigger?
- Have you already used up other Section 179 property purchases this year, pushing you toward the phase-out threshold?
If your only reason for buying is the write-off, year-end planning usually reveals better options, whether that's timing the purchase into the following tax year or choosing a lease instead, which carries different tax treatment entirely. A vehicle purchase should fit a multi-year plan, not solve a one-time tax problem.
What Counts as a '6,000 lb Vehicle' Under IRS Rules?
The term doesn't refer to how heavy the vehicle feels or what the manufacturer calls it in a brochure. It refers specifically to the gross vehicle weight rating, a number set by the manufacturer that represents the vehicle's maximum loaded weight, including passengers, cargo, and fluids. That figure appears on a certification label on the driver's side door jamb.
A vehicle qualifies for the SUV-specific $32,000 Section 179 cap when its GVWR falls between 6,000 and 14,000 lbs. Below 6,000 lbs, you're back under the restrictive luxury-auto depreciation limits set by §280F. Above 14,000 lbs, different rules apply, and in many cases the vehicle can qualify for full expensing without the SUV cap at all, since it's treated more like heavy equipment than a passenger vehicle.
One detail trips up more buyers than anything else: curb weight and GVWR are not the same number, and dealers don't always volunteer the distinction. A half-ton pickup might have a curb weight around 5,000 lbs but a GVWR comfortably over 6,000 lbs once you factor in payload and towing capacity. Confirming the manufacturer's GVWR specification before you assume eligibility saves you from an unpleasant surprise when your preparer pulls the actual spec sheet. Ask for the GVWR in writing from the dealer, or better, check the door jamb sticker yourself before you finalize the purchase.
Which Vehicles Typically Meet the 6,000 lb GVWR Threshold?
Full-size pickup trucks clear the 6,000 lb threshold routinely. Half-ton trucks like a Ford F-150, Chevrolet Silverado 1500, or Ram 1500 generally have a GVWR well above 6,000 lbs once equipped with a standard cab and bed configuration, though exact figures shift by trim and drivetrain.
Large SUVs are where the deduction gets its reputation, and where the G Wagon tax write-off conversation usually starts. Vehicles like the Chevrolet Suburban, GMC Yukon XL, Ford Expedition, and larger luxury SUVs including the Mercedes-Benz G-Class frequently carry a GVWR over 6,000 lbs. That's precisely why the SUV-specific $32,000 cap exists in the first place: without it, a business owner could write off the entire cost of a six-figure luxury SUV in year one, simply because it happened to weigh enough to dodge the passenger-auto limits.
Cargo vans and box trucks used for delivery or trade work often exceed 6,000 lbs GVWR as well, and depending on configuration, some qualify for full expensing outside the SUV cap entirely if they meet specific IRS criteria for vehicles not designed for personal use, such as having no seating behind the driver or a fully enclosed cargo area.
The specific trim, cab size, bed length, and drivetrain all affect the final GVWR number, so two versions of the same model can land on opposite sides of the 6,000 lb line. Always verify the exact configuration you're buying, not just the model name, against the manufacturer's published specifications.

Can Modifications Change a Vehicle's Weight Eligibility?
Aftermarket modifications can shift a vehicle's classification, and not always in the direction owners expect, so understanding the incentives and bonus depreciation available on qualifying business electric utility vehicles can be crucial, as explained in this detailed guide. Adding heavy equipment, such as a service body, tool boxes, a plow mount, or a permanent equipment rack, increases the vehicle's gross weight and can push a borderline vehicle over the 6,000 lb threshold if it was close to begin with.
The reverse matters too. Removing seats, installing a permanent divider, or converting a passenger SUV into a cargo configuration can affect whether the vehicle is treated as a passenger automobile or a vehicle designed primarily for cargo, which changes which depreciation rules apply.
What modifications generally cannot do is change the manufacturer's base GVWR rating itself. GVWR is a safety and engineering specification tied to the chassis, suspension, and braking system as designed, not something you increase simply by adding a heavier bumper. A vehicle rated at 5,900 lbs GVWR from the factory doesn't become a 6,000 lb vehicle because you bolted on a truck bed toolbox. If a vehicle is right at the edge of the threshold, get the exact GVWR confirmed in writing from the manufacturer or a certified weight station rather than assuming aftermarket work moved the needle.
How Does This Deduction Interact With Luxury Auto Limits?
This is the entire reason the 6,000 lb threshold exists as a planning lever. Standard passenger automobiles are subject to strict annual depreciation caps under §280F, with limitation tables published in Rev. Proc. 2025-16 that cap first-year depreciation on a typical car at a few thousand dollars, regardless of the purchase price. That cap exists specifically to prevent business owners from writing off six-figure luxury cars in a single year.
Vehicles with a GVWR over 6,000 lbs are exempt from those §280F passenger-auto limits. Instead, they fall under the separate $32,000 SUV cap for Section 179, with bonus depreciation available on top of that for the remaining basis. This is precisely why a heavy luxury SUV can generate a dramatically larger first-year deduction than a luxury sedan costing the same amount, even though both are "expensive vehicles" in a colloquial sense.
The overall Section 179 dollar limits still apply on top of the vehicle-specific cap. If your business places more than $4,090,000 of qualifying property in service in 2026, your total Section 179 deduction begins phasing out dollar for dollar, and a heavy vehicle purchase counts toward that total alongside equipment, machinery, and other qualifying assets. Businesses making large capital investments in the same year need to run the numbers before assuming the full $32,000 SUV cap will be available.
Passenger Vehicles vs. Non-Passenger Vehicles: Why the Distinction Matters
Not every vehicle with a heavy GVWR gets treated the same way, and this is where the deduction math can diverge sharply. The IRS separates heavy vehicles into two practical categories for depreciation purposes: SUVs and similar vehicles designed for passenger transport, and vehicles built primarily for cargo or specific work use.
SUVs, large pickups with a rear seat, and similar passenger-style vehicles with a GVWR between 6,000 and 14,000 lbs fall under the $32,000 Section 179 SUV cap, regardless of how heavy they get within that range. A $150,000 luxury SUV and a $50,000 SUV are both subject to the same $32,000 Section 179 ceiling, though both can still claim bonus depreciation on the remaining basis.
Vehicles that meet specific criteria for non-passenger use, such as a cargo van with no seating behind the driver, a vehicle with an open cargo bed at least six feet long, or a specialized work vehicle not readily adaptable to personal use, can bypass the SUV cap entirely. These vehicles may qualify for full Section 179 expensing up to the general dollar limit, plus 100% bonus depreciation, without the $32,000 ceiling applying at all.
That distinction is worth confirming before you buy, not after. A crew-cab pickup with a short bed and a back seat full of passenger seating gets treated very differently from a regular-cab work truck with a long open bed, even if both weigh roughly the same and cost about the same.
Do State Taxes Change How This Deduction Works?
Federal rules set the framework, but not every state follows the federal Section 179 and bonus depreciation numbers exactly. Some states conform fully to federal depreciation rules, some conform on a delayed basis, and others decouple entirely, setting their own lower caps or disallowing bonus depreciation for state income tax purposes even when it's fully allowed federally.
That means a business owner in one state could take the full federal deduction on their federal return while facing an addback adjustment on their state return, effectively spreading part of that deduction over several years for state purposes even though it's gone federally in year one. Businesses operating in Idaho and Oregon should confirm current state conformity rules with a preparer familiar with both jurisdictions, since these rules shift periodically as state legislatures update their own tax codes.
If your business operates across multiple states, or if a vehicle is registered in one state but used for work that spans several, the state-level treatment of the deduction deserves its own conversation before you finalize a purchase, not an afterthought after you've already filed.
What Melissa Korber Has Learned Advising Clients on Vehicle Deductions
The vehicle deduction conversation almost always starts the same way: a client wants to know if buying a truck this year will lower their tax bill. It usually can. The more useful question is whether that truck fits into a multi-year strategy or whether it's a reaction to a big income year that creates a recapture headache in three years when the vehicle gets traded in.
The clients who get the most value treat the vehicle as one piece of a broader plan, not a standalone move. The ones who run into trouble bought based on a rumor about a "G Wagon tax write off" without checking their actual business-use percentage first. Structured, ongoing advisory catches that gap before the purchase, not during an audit.
— Melissa
Get Audit-Proof Vehicle Deduction Planning From The Tax Refinery
A heavy vehicle deduction only pays off if it survives scrutiny three years later, and that requires planning before the purchase, not a scramble at tax time. Thetaxrefinery builds that planning into ongoing engagements instead of a once-a-year filing conversation, so your business-use percentage, entity structure, and documentation are all lined up before you sign for the vehicle.
If you run an S corporation and the vehicle purchase intersects with your entity structure, the S-Corp Tax Strategy Accelerator addresses how the deduction flows through to your personal return alongside your reasonable-compensation and accountable-plan setup. For owners who want the vehicle purchase evaluated as part of a full-year strategy rather than a one-off form, Monthly Tax Advisory and Quarterly Tax Strategy Sessions build the recordkeeping, mileage-log discipline, and recapture modeling into your regular planning cycle instead of leaving it to guesswork in April. Reach out to Thetaxrefinery for a personalized assessment of your vehicle purchase and an audit-ready documentation plan before you finalize the deal.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What Is the Section 179 Limit for a 6,000 lb Vehicle in 2026?
The Section 179 cap for SUVs with a GVWR between 6,000 and 14,000 lbs is $32,000 for 2026, according to Publication 946. Bonus depreciation can then apply to the remaining business-use basis after that cap is applied.
Does a Truck Need to Weigh Exactly 6,000 lbs to Qualify?
No, the vehicle needs a manufacturer GVWR of 6,000 lbs or more, up to 14,000 lbs, to access the SUV-specific Section 179 cap and escape passenger-auto depreciation limits. Check the door jamb sticker or manufacturer specification sheet rather than estimating.
Can I Deduct 100% of a Heavy Vehicle's Cost?
Section 179 covers up to $32,000, and bonus depreciation at 100% under the OBBB rules can cover the remaining business-use basis.
What Happens if I Sell the Vehicle Early?
This is one of the most common surprises practitioners see, and it's worth modeling before the sale, not after.
Does The Tax Refinery Help With Vehicle Deduction Planning?
Yes, Thetaxrefinery builds vehicle deduction strategy into its ongoing advisory engagements, including entity-level planning for S corporations through the S-Corp Tax Strategy Accelerator. Current pricing for advisory and tax preparation services is listed on the fee schedule.